AI Pitched Her an $18,740 Roof. The Repair Cost $1,460
After a storm, public records, weather data and an image model made a roof replacement pitch feel like a diagnosis. The house needed work, but not the work in the proposal.
October 3, 2026 · 7 min read
The line Helen could not make sense of was near the top of a four-page proposal: “Estimated roof age: 22 years.”
She was 74 and had lived in the house for 31 years. She remembered replacing the roof because she had kept the receipt in a folder with appliance manuals and tax records. The work had been done 16 years earlier.
The age mattered. It helped explain the total printed at the bottom of the proposal, $18,740, and it supported the salesperson’s claim that a recent windstorm may have pushed an old roof past the point where a small repair made sense. One item allowed $4,980 for removing the existing shingles. Another put underlayment at $2,240.
Helen had not called the company. It had contacted her four days after the storm.
The first message referred to the approximate age of her house, the roof’s size and wind recorded near her neighborhood. A later email included an aerial image with a marked section above the back bedroom. The text said that homes with similar roofs in the storm path could have damage that was hard to see from the ground.
It did not read like a general advertisement. It read like someone had looked at her house.
Her adult son called it a scam as soon as she forwarded it. Helen thought that was too easy. Two shingles had landed near the side fence after the storm, and a stain had appeared above a closet during heavy rain the previous winter. The company might have found her through an unsettling method and still be right about the roof.
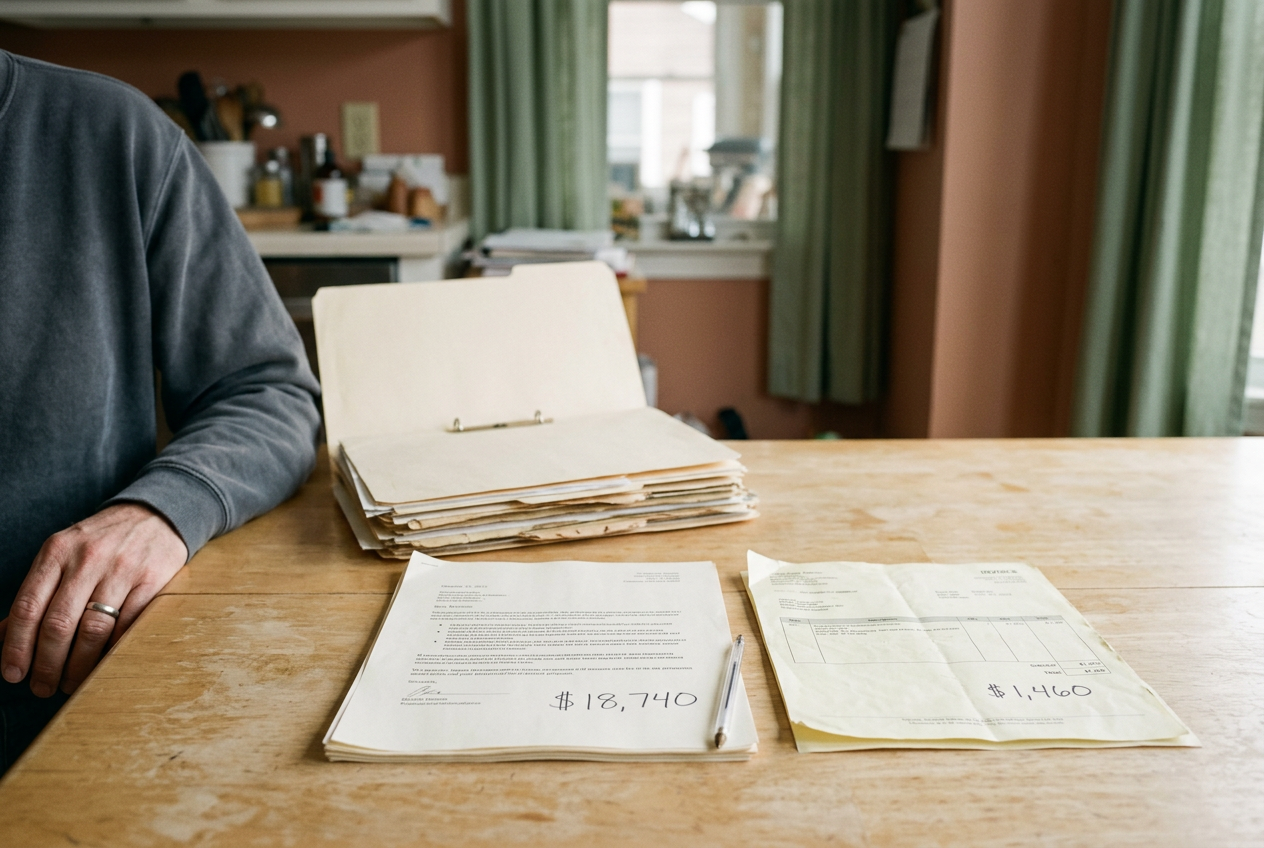
She set the $18,740 proposal on her kitchen table and left it there for nine days.
How the house became a sales lead
The salesperson later showed Helen and her son a screen used to prepare the visit. Her address had a lead score of 87 out of 100. He described the software as a tool that found homes likely to need roofing work and drafted messages for their owners.
That score was not a measurement of damage. It was a prediction about the value of contacting the household.
Systems used for this kind of sales work can combine county property records, building permits, real estate listings, aerial or satellite images, storm maps and purchased household data. A model may estimate roof shape and surface area from an image, assign a probable roof age when records are incomplete, then raise a lead’s rank when hail or strong wind has been reported nearby.
The system can also infer who may be ready to buy. Long ownership can suggest that a homeowner has equity. Assessed value can stand in for the likely size of a job. Consumer data may place residents in broad age or income bands, even when the contractor never sees a birth date or bank balance.
The company would not give Helen a formula for the 87. The salesperson’s screen showed categories instead: roof age, storm exposure, property value and signs of exterior wear. The software had treated the roof as older than Helen said it was, while the image analysis had marked a dark patch near the back bedroom as possible deterioration.
A basic mailing list could have found every house in the ZIP code. The AI did more. It selected Helen’s property, assembled separate pieces of data into a claim about need, chose details likely to make that claim credible, and produced language that sounded written after a review of her house.
That combination changed the encounter. Helen did not receive a coupon for roofing. She received what looked like an assessment, although nobody had yet touched a shingle.
What the system got wrong
The roof was not 22 years old. The public permit history available to the sales system did not clearly match the replacement in Helen’s folder, so the software appears to have fallen back on an estimate based on other records and the roof’s visible condition.
The marked patch in the aerial image was not storm damage either. An independent inspector later identified it as a mix of shade and surface growth near an overhanging branch. Image models can find color and texture differences across thousands of roofs, but they do not know from pixels alone whether a dark area is moisture, dirt, shade, aging material or a harmless difference in how the image was captured.
The weather claim had a similar limit. A storm map could place the property inside an area of estimated wind or hail exposure, but it could not show that a particular shingle had lifted. Weather services often build those maps from radar, reports and modeled paths rather than a sensor on each house.
None of those errors made the roof sound uncertain in the sales message. The model’s estimates had been turned into ordinary sentences, and ordinary sentences tend to shed the warnings attached to data. A probability became an estimated age. A patch became possible wear.
A storm near the property became a reason to act before more rain arrived.
Helen kept returning to the $18,740 proposal because it gave the uncertain claims a solid ending. The total was precise even where the evidence was not.
The salesperson did climb onto the roof during the visit. He took photographs of loose material near a vent and worn shingles along one slope. Those conditions were real, though the proposal did not separate damage caused by the recent storm from wear that had developed over years.
Helen’s son still wanted her to discard the papers. She did not. The stain above the closet remained, and the two shingles near the fence had come from somewhere.
A real repair inside an inflated conclusion
Helen paid $275 for an inspection unconnected to the company that had approached her. That inspector found lifted shingles and failed flashing near a vent. He did not find signs that the roof deck was failing, and he did not recommend replacing the whole roof at that point.
A local contractor later quoted $1,460 to replace the damaged section and redo the flashing. Helen accepted that work. The contractor also told her the roof was in the later part of its expected life, which meant the $18,740 proposal was not describing an impossible future expense. It had moved that expense forward and attached it to one storm.
Her result cannot establish what another house needs. Roof condition depends on materials, installation, weather and maintenance, and estimates can differ even after in-person inspections. What her paperwork shows is narrower: the system was good enough to find a homeowner with a plausible problem, but not good enough to determine the scale or cause of that problem.
That distinction was worth $17,280 in Helen’s case.
She did not come away believing the first company had invented everything. Its software had found the age range of her house, calculated a credible roof size and connected the address to recent weather. It had also helped the salesperson arrive prepared, without spending days driving street by street looking for loose shingles.
The useful parts made the errors harder to dismiss.
The privacy cost of a convincing message
Most of the property details in Helen’s message were not secret. Home size, assessed value, sale history and some permit information can be public. Storm data and overhead images are widely sold. Household details may come from data brokers that group people by likely age, ownership status or purchasing power.
Helen had encountered each category separately before. She had looked up her tax assessment online and seen aerial images of the neighborhood. What unsettled her was the assembly: one system had joined the house, the storm and an inferred description of its owner, then used that package to decide she was worth pursuing.
Her son searched the message and found no clear account where she could inspect the underlying data. The company removed her from its marketing list after she requested it, but that did not alter county records, weather databases or copies held by other sellers. She never learned which source supplied the mistaken roof age.
The four-page proposal stayed in her folder after the $1,460 repair was finished. She wrote “no replacement” beside the total and clipped the new contractor’s invoice behind it.
Questions people ask
Is an
AI-personalized roof message proof of a scam?
No. In Helen’s case, the message came from a working contractor and pointed toward a real roof problem. The concern was that automated estimates and public data made a sales pitch look more like a completed inspection than it was.
Can
AI tell whether a storm damaged a specific roof?
It can connect an address to modeled weather, estimate roof features from images and flag visible differences. Helen’s case showed the limit: the system could identify a plausible candidate for damage, but an in-person inspection was needed to distinguish storm damage from shade, surface growth and older wear.
Why did the company know the age and value of the house?
Those details can come from property assessments, sale records, permits, listings and commercial data. The system combined them with weather history and image analysis, then used the result to rank Helen as a strong sales lead with a score of 87 out of 100.
Why was the replacement price so much higher than the repair?
The two prices covered different conclusions. The $18,740 proposal assumed the roof should be removed and replaced, while the $1,460 invoice covered damaged shingles and flashing near one vent. Helen kept both papers together, with “no replacement” written on the larger proposal.
One story a day
The story of the day, in your inbox
One real story about AI each morning — no hype, no alarm, just company for the road.