AI Flagged Her $500 Savings Circle. An Officer Overrode It.
Six relatives saved $500 each month and took turns receiving the pool. A loan model saw unstable cash flow until an officer matched the transfers to a notebook.
September 22, 2026 · 8 min read
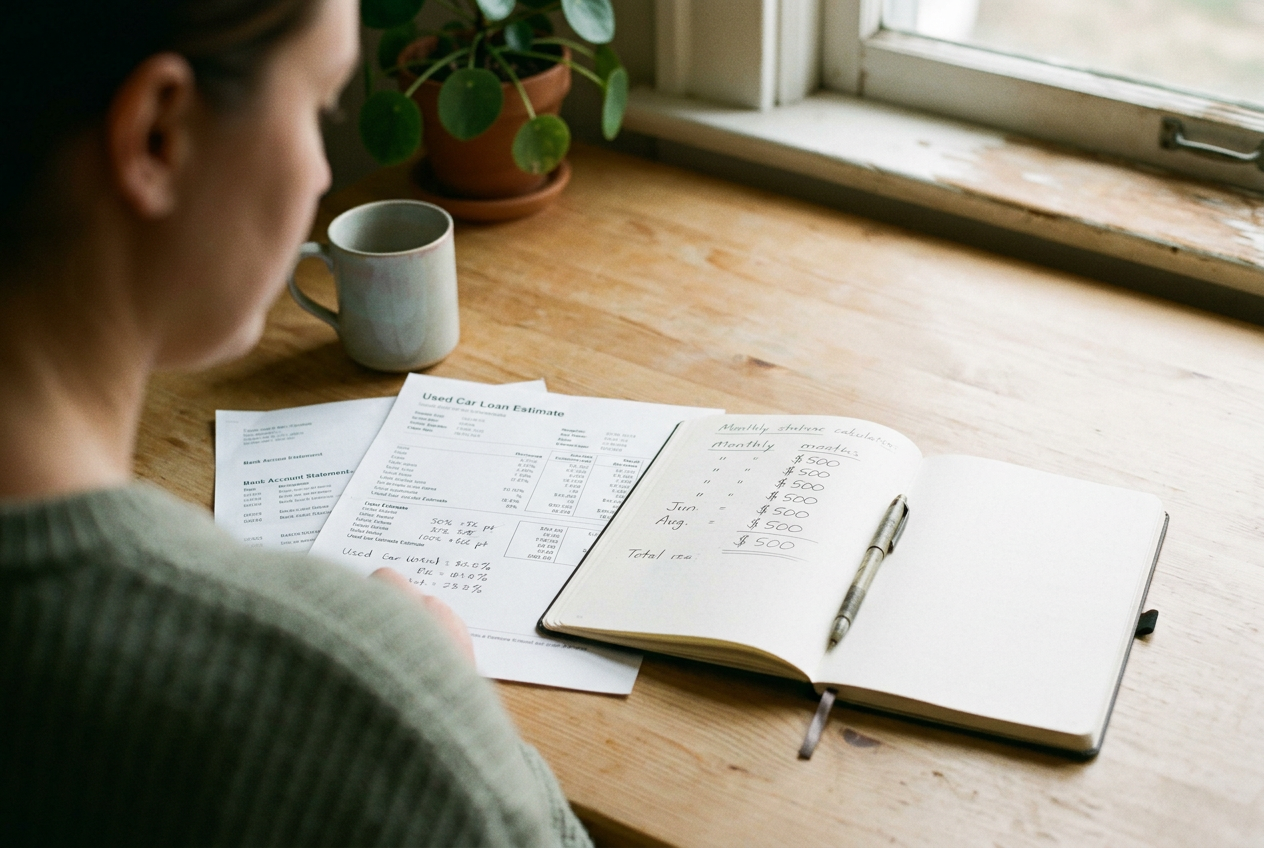
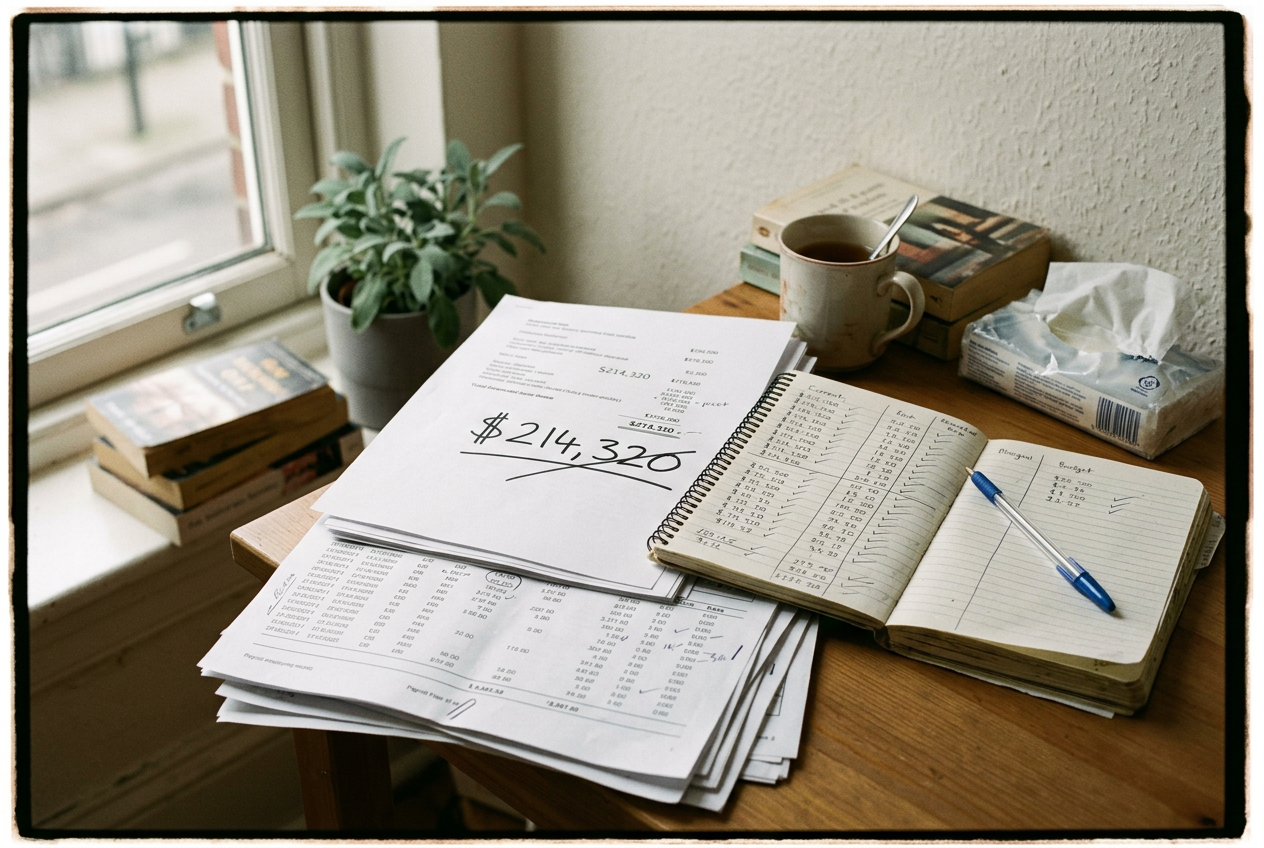
Renee brought a notebook to the credit union because she thought someone might ask about the $3,000 deposits.
Six relatives had been saving together for three years. Each person contributed $500 a month, and one person received the full pool. Renee’s notebook recorded the month and recipient, with a check beside each payment. Her turn came every six months.
She was applying for a $19,800 used-car loan. She had $4,000 for the down payment, earned about $4,580 a month before taxes and had worked for the same employer for four years. Her credit history showed no missed loan payments. The first concern came from somewhere else.
The credit union used a machine-learning model to review account activity alongside conventional credit information. Its dashboard gave Renee a weak cash-flow stability score and marked her person-to-person transfers for review. The model had examined twelve months of transactions, recognizing her paycheck as regular income while treating the $500 transfers as recurring outflows and the $3,000 pools as irregular deposits.
On the screen, the result looked tidy. The notebook told a different story.
What the model counted
Cash-flow underwriting starts with transactions rather than relying only on a credit report. Software groups deposits and withdrawals into categories, estimates which ones will repeat and calculates how much money appears to remain after regular obligations. A machine-learning model can compare those features with patterns found in past borrowers whose loans were repaid or went delinquent.
That can reveal facts a credit score misses. A person with a short credit history may still have a steady paycheck, stable rent payments and money left near the end of each month. Someone with a strong credit score may have developed a recent overdraft pattern that has not reached a credit bureau.
Renee’s problem came from the way the model separated incoming money from outgoing money. Her paycheck had a consistent description and arrived on a regular cycle. The transfers from relatives had different sender names and appeared only when it was her turn to collect the pool. The system did not treat those deposits as income it could rely on.
The monthly $500 payments received a different treatment. They left Renee’s account with regularity, often through the same transfer service, so the model assigned them a higher chance of recurring. In effect, it counted the contribution as a continuing obligation while giving little weight to the money Renee periodically received back.
That pushed down the model’s estimate of her available cash. The transfers also made her monthly inflows appear more volatile, one of the combinations the system associated with higher repayment risk.
No employee had written a rule stating that savings circles were dangerous. The result came from statistical relationships learned from prior account records, where frequent person-to-person transfers might have accompanied informal debts, emergency borrowing or households moving money to cover shortages. The model could recognize the shape of those transactions without knowing why they existed.
A spreadsheet could have totaled the amounts incorrectly. This system did something more consequential: it inferred that the pattern predicted future strain, placed that inference inside a risk score and made the score available before any person had read the statements.
The notebook beside the score
The loan officer used the model on most applications. It condensed months of account activity and often directed her attention to recent overdrafts or loan payments that would take much longer to find by reading every line. She did not regard every flag as a rejection, though a low stability score required her to explain why she approved a loan despite it.
Renee opened the notebook to the latest six-month cycle. Five relatives had checkmarks beside $500 contributions during the month she received the pool. The total was $3,000. Earlier pages showed the same structure, including two months when another relative received the money and Renee’s own $500 left her account.
The officer compared those entries with eighteen months of statements. A $500 transfer appeared each month. Every sixth month, transfers totaling $3,000 arrived from the group. The recipient changed according to the notebook, but the amount did not.
Renee described the pool as savings that was harder to spend. She could withdraw money from an individual savings account whenever she wanted. The circle gave her a date and five other people who expected her contribution.
The distinction mattered to the loan decision. If the $500 was an informal debt payment, Renee would still owe it without receiving anything later. If the $3,000 deposits were emergency help, they might suggest that her wages did not cover ordinary expenses. The notebook showed a reciprocal arrangement with a fixed cycle, and the account history supported it without requiring the officer to accept the explanation on trust.
The officer recalculated Renee’s monthly obligations without treating the full contribution as debt. She still considered the $500 because it continued to leave the account, but she also looked at Renee’s balance after each transfer and at the repeating return of the pool. Renee had not overdrawn the account during the eighteen months under review. Her lowest month-end balance was $1,140.
The model could not make that interpretation by itself. It had transaction descriptions, amounts and timing. It did not have the notebook, the family agreement or a reliable label for rotating savings. Even if training data contained other savings circles, those transactions might have been recorded through cash, different payment services or descriptions too varied for the model to connect.
The override
The officer approved the $19,800 loan after documenting why the cash-flow signal overstated the risk. The term was five years, and the monthly payment came to about $393. Renee kept enough of her $4,000 down payment fund to cover registration and the first insurance bill.
The approval was not a declaration that the model had no value. Its flag caused the officer to examine transfers that did affect Renee’s monthly budget, and the score prevented the application from passing without review. The failure was narrower: the model assigned meaning from regularity alone, then treated the outgoing and incoming sides of one arrangement as though they belonged to separate stories.
That asymmetry can be difficult to spot at scale. Transaction models often work with features rather than complete human-readable accounts. An officer may see a score, a category and the transactions that contributed most, but not a sentence explaining the model’s full reasoning. Hundreds of small relationships between timing, balances and transaction types can influence the result.
The override created a record of one human decision. It did not mean the model would understand the next applicant’s savings circle. The credit union could review overrides for recurring patterns and adjust its transaction categories or training process, but Renee was not told that her notebook would change the system. Her loan moved forward.
The score remained on the dashboard.
She also stayed in the circle. Two months after buying the car, she sent another $500 to a relative, and the transfer looked much like the ones the model had already counted. In the notebook, it received one checkmark.
Questions people ask
Can an
AI loan model mistake transfers between relatives for debt?
Yes. A cash-flow model may treat regular person-to-person payments as recurring obligations, especially when transaction descriptions do not explain the relationship. It may also discount occasional incoming transfers because they do not resemble wages. In Renee’s review, those two treatments made one savings arrangement look like continuing financial strain.
Does a low automated cash-flow score automatically mean a loan is denied?
That depends on how a lender uses the score. At this credit union, the result sent the application to a loan officer rather than producing a final denial. The officer could approve the loan after comparing the flagged transfers with statements and recording why the model’s interpretation did not fit the account history.
Why could the system recognize paychecks but not a savings circle?
Paychecks tend to arrive from one source with repeated descriptions and timing, which gives transaction software a strong category. Renee’s pool arrived from several people only once every six months. The model detected the amounts, but it lacked the family agreement that connected the irregular deposits to her regular $500 payments.
What evidence changed the loan officer’s decision?
The officer matched eighteen months of statements to Renee’s notebook. It showed a $500 contribution each month and a $3,000 pool returning on a six-month cycle, while the statements showed no overdrafts. After the loan closed, the next family transfer added another checkmark to the notebook.
One story a day
The story of the day, in your inbox
One real story about AI each morning — no hype, no alarm, just company for the road.