A Chatbot Guaranteed a Resident $214,320 in Loan Forgiveness
The debt assistant calculated a medical resident’s federal loan forgiveness, then presented a conditional outcome as settled. Her payroll record showed what the bot had missed.
September 21, 2026 · 8 min read
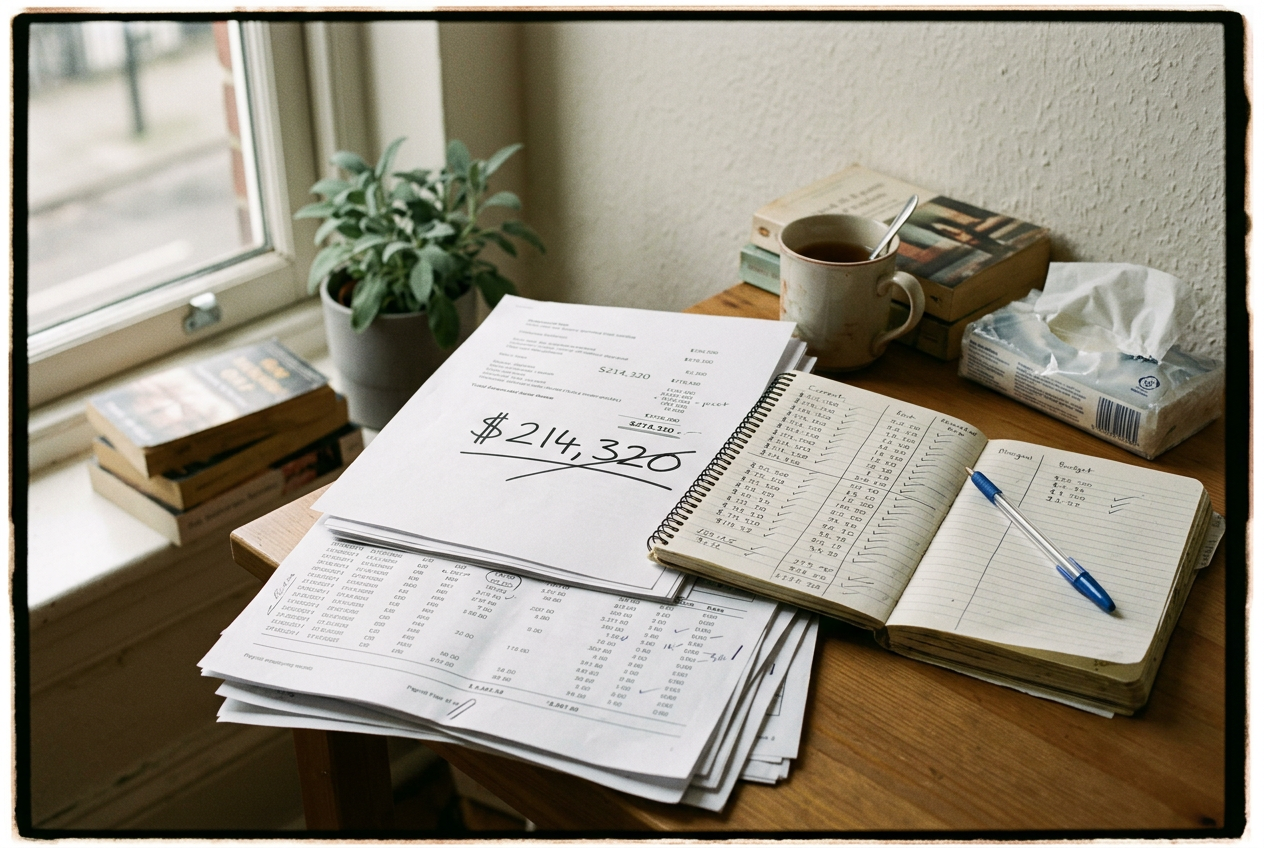
The number sat near the top of a page she had printed from her debt dashboard: $214,320.
Below it were projections for monthly payments and the remaining balance after 120 eligible payments. The page treated federal loan forgiveness as the expected end of the calculation, not one possible result. She folded it once and carried it in the same folder as her hospital onboarding papers.
The resident had finished medical school with $286,400 in federal student loans. Her average interest rate was about 7 percent, and her first-year salary was $67,800. She was about to begin making payments in March 2024, when rent, licensing costs and a move had already reduced her checking account to $3,600.
She had used repayment calculators before. They required her to select assumptions from menus, then displayed several outcomes. This tool worked as a conversation. It had access to the balances on her account, and she typed in her salary, marital status and workplace description.
She described the hospital as a nonprofit teaching hospital.
The assistant recommended an income-driven repayment plan and estimated a required payment of $418 a month. It also treated her residency as qualifying employment for Public Service Loan Forgiveness, the federal program that can cancel remaining Direct Loan balances after a borrower makes 120 qualifying monthly payments while working full time for an eligible public or nonprofit employer.
When she asked whether the projected forgiveness depended on anything else, the bot repeated the conclusion with more confidence. Its replies paraphrased the program rules, but the central point did not change: after 120 payments, the remaining $214,320 would be forgiven.
She changed plans.
The employer on the paycheck
Four months later, a payroll employee mentioned that residents were not employed by the hospital whose name appeared on the building. Their paychecks came from an affiliated physician group that handled the training program.
The distinction had not mattered to her before. She worked in the hospital, wore its identification and used its computer system. The debt assistant had accepted the workplace description she supplied and carried that description through the rest of the conversation.
She opened the federal student aid site and searched for the employer printed on her tax record. The teaching hospital appeared in the official employer database. The physician group did not produce the same clear result.
The federal guidance focused on the organization employing the borrower, generally identified through the tax number on payroll documents, rather than the building where the work occurred. Some contractors and affiliated groups can have different status from the hospitals they serve. The chatbot had not asked who issued her paycheck or requested the identifying information needed to check.
She took the printed dashboard page from her folder. The $214,320 figure was still there, although one of the facts supporting it was now uncertain.
Her repayment plan itself was eligible under the federal program as described on the official site. Her federal loan type also fit. Employment was the unresolved part, and employment had been the fact the assistant sounded most certain about.
She sent documentation through the federal servicing process used to confirm qualifying work. The response did not validate the entire residency period. More records were needed to determine how the physician group related to the hospital and whether her employment met the program’s requirements.
That was not a rejection. It was also not the guarantee on the dashboard.
A calculation joined to a guess
The $214,320 estimate looked precise because much of the arithmetic was precise. The tool knew her current principal and interest rates. It could project payments from the income she entered, estimate balance growth and subtract 120 monthly payments from a modeled loan balance.
The weak point came earlier. To place forgiveness at the end of that calculation, the assistant had to treat her future payments as qualifying and her employer as eligible, even though it had only the ordinary phrase “nonprofit teaching hospital” rather than the payroll identity used by the federal program.
A conventional calculator might have labeled employer eligibility as an assumption or left the forgiveness field blank. The conversational system did something different: it turned her description into a likely category, then generated a fluent explanation around that category. Her follow-up questions did not force a fresh verification. They gave the system more opportunities to restate the same premise in reassuring language.
This is a common failure mode in chat-based financial tools. A language model generates a response that fits the user’s words and the surrounding conversation. It may be connected to a calculator or a set of program summaries, but that does not mean every personal fact has been checked against the official record that controls the outcome.
The machine did not invent the forgiveness program or misunderstand all its rules. It compressed a conditional chain into a promise. Direct Loans, an eligible repayment plan, qualifying payments and qualifying employment became a single projected number, while future job changes and the identity of the employer disappeared from view.
That compression mattered to her because the conversation felt like an individual review. The assistant referred to her salary and balance. It adjusted the monthly estimate when she changed her household information. Those correct personal details made the unverified employment conclusion look equally personal and equally checked.
A bad spreadsheet could have produced faulty arithmetic. This mistake required the chatbot’s conversational inference: it interpreted a plain-language workplace description, treated the most likely institutional arrangement as her actual arrangement and defended that conclusion when asked again.
Four months on the new plan
During the first four months, she paid $1,672 under the income-driven plan. About $6,700 in interest accrued over the same period, leaving her balance roughly $5,000 higher than when repayment began.
That increase did not prove the plan was wrong. Income-driven plans can produce balances that rise when required payments do not cover monthly interest, and forgiveness can still make that tradeoff useful for borrowers whose employment and payments qualify. Her problem was that she had accepted the tradeoff as settled before the employment question had been answered.
She did not immediately leave the plan. The standard monthly payment shown on her federal account was more than $3,000, which did not fit her resident salary. Instead, she changed the way she recorded the debt in her own budget.
Her spreadsheet had contained a line labeled expected forgiveness, with $214,320 entered as though it were an asset arriving later. She deleted that figure. In its place, she added a note that the employment period remained unconfirmed and began transferring $250 a month to a separate savings account while the review continued.
This was her response to her own circumstances, not a recommendation for another borrower. Federal repayment costs depend on income, loan history and rules that can change. The useful distinction in her records was narrower: one number came from a modeled outcome, while the other information came from the agency responsible for deciding whether her work counted.
Eight months after the first chatbot conversation, part of her residency employment had still not been formally confirmed. She had kept the income-driven plan because it remained affordable and because later work at a different nonprofit institution might qualify even if the earlier period did not.
She also kept using the debt assistant. It was good at summarizing balance changes and showing how a higher salary could alter projected payments. She stopped using it to settle questions that depended on records it could not see.
The printed page stayed in her folder. She crossed out $214,320 with one line but left the number readable.
Questions people ask
Is
Public Service Loan Forgiveness guaranteed after 120 payments?
The program forgives remaining eligible federal loan balances when its requirements are met, but a projection cannot establish in advance that every payment or employment period will qualify. In the resident’s case, the assistant modeled 120 payments while assuming that the organization on her payroll record was an eligible employer.
Does working at a nonprofit hospital make a resident eligible?
The worksite alone did not answer that question in this story. The resident worked inside a nonprofit hospital, but an affiliated physician group issued her paycheck. The federal review depended on the employing organization and its status, which the chatbot had inferred from her description rather than verified from payroll records.
Why did the chatbot give such a precise forgiveness amount?
It combined reliable account figures with unverified assumptions. Her balance, interest rates and entered salary supported detailed payment calculations, while employer eligibility came from a conversational description. The resulting $214,320 looked like one measured fact even though part of it rested on a guess.
Did she stop using the AI debt assistant?
No. She continued using it to summarize balances and compare modeled payments, tasks she could check against her account. She treated its claims about federal eligibility differently and kept the crossed-out $214,320 printout with the agency correspondence in her folder.
One story a day
The story of the day, in your inbox
One real story about AI each morning — no hype, no alarm, just company for the road.