A Teacher’s Old Address Added $612 to Her Insurance Quote
After a divorce and move, an automated insurance system treated a teacher’s former home as an active risk. A manual review cut the annual quote from $2,184 to $1,572.
October 13, 2026 · 7 min read
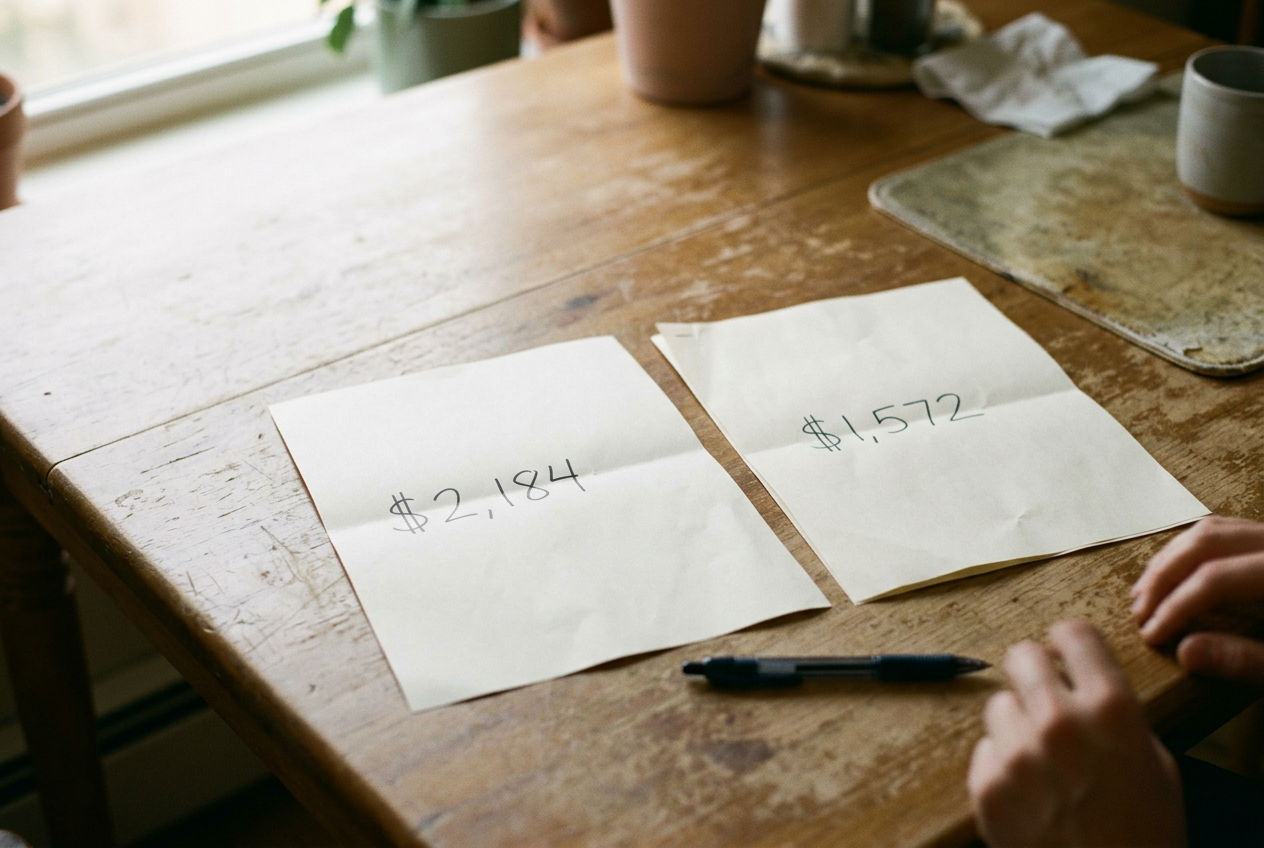
In August 2024, Elena sat at her kitchen table with a one-page auto insurance quote showing an annual price of $2,184. She had expected something near $1,600, based on the joint policy she had recently left and an earlier estimate from the same insurer.
One line held her attention. The quote showed two active address links: her rental and the house where she had lived with her former husband.
Elena, a public school teacher, had moved out fourteen months earlier. The old house was eleven miles away. Her name was no longer on its utility account, her car stayed at the rental, and the insurer’s customer profile displayed only the new address.
Still, the old house had reached the price.
The quote sheet became her record of what followed. She wrote “old address” beside the $2,184 total and kept it on the table, where she returned to it after classes and grading. The issue looked like a stale entry. It was more than that.
The system made a new inference from old facts
Many automated insurance quotes rely on two distinct kinds of computation. One tries to decide which records belong to the same person or household. Another estimates the likelihood and expected cost of future claims.
The first task is often called identity resolution or entity matching. A system compares pieces of information across policy files, consumer reports, prior addresses and other permitted sources. Exact matches are easy. The harder cases involve changed names, shared policies, abbreviated addresses and people who once lived together but no longer do.
Instead of requiring every field to match, a machine-learning model can assign weight to partial overlaps. An address shared for nine years may count strongly. A policy that remained joint during a separation may reinforce the link. A vehicle renewal or another record arriving after the move may make the former household appear current, even when the applicant has entered a new home address.
That was the load-bearing machine decision in Elena’s quote. The system did not merely retrieve an outdated row and print it. It compared conflicting records, judged that the former address still represented an active connection, and passed that conclusion into the pricing process.
A spreadsheet could store the wrong address. It would not, on its own, calculate the probability that Elena still belonged to a household she had left.
The second system turned that inferred connection into risk features. Insurers do not all use the same inputs, and the details of a model are rarely visible on a consumer quote, but location can affect expected losses through patterns such as claim frequency, repair costs and vehicle theft. Household links can also change which drivers, vehicles or prior losses appear relevant to a policy.
Elena’s former address was in a different rating area. A vehicle still associated with that household had also been involved in a claim after she moved. The quote engine did not say that either fact added a particular number of dollars. Pricing models usually evaluate features together, so even an employee reviewing the file could not separate the premium into a clean charge for each signal.
What Elena could see was the output: $2,184, with two addresses feeding the quote.
Her account page and her risk profile disagreed
The contradiction made the problem difficult to explain. Elena’s visible profile was correct. Her mail went to the rental, and the car’s listed location matched it. When she checked the account page, the old house was absent.
Behind that screen, the quoting system had access to a broader address history and a confidence score for each link. A current mailing address answers where correspondence should go. An identity model is trying to answer a different question: which homes, people and vehicles might still belong together for risk purposes.
Those answers can separate after a divorce. Everyday records do not update in one coordinated moment. A joint policy may continue until renewal. A vehicle title may change later than a utility account.
Some data sources mark an address as historical, while another sends a recent record carrying the same household connection.
The model can treat recency as evidence, but recency does not explain the life event behind a record. It sees that a link appeared again. It does not know that the appearance came from closing a shared account, transferring a car or finishing paperwork that had been delayed during the school year.
This is one reason probabilistic matching can fail with confidence. The system is built to connect records despite small inconsistencies, which is useful when someone leaves an apartment number off an application or changes a last name. That same tolerance can preserve a relationship that has ended.
Elena did not object to the insurer checking where her car was kept. That part made sense to her. She objected to being asked to accept a price based on a household connection that the company’s own account page did not show.
A manual review changed the link
Elena contacted the support team through the account page and described the two-address line on the quote sheet. The first response focused on confirming her mailing address. She replied that the mailing address was already correct and that the quote appeared to be using the former home as an active risk link.
That distinction moved the issue to a manual review.
The reviewer asked for material showing when Elena had moved and where the car was normally kept. She provided part of her lease and a prior policy page. She covered unrelated financial details before uploading the files, but the exchange still required her to share documents containing her home address and signature because an automated system had joined records she could not inspect directly.
She chose not to send her divorce agreement. The lease and policy record were enough for this review.
After nine days, the insurer removed the former address from the active household grouping and generated another quote using the same coverage choices and deductibles. The new annual price was $1,572.
Elena placed the second sheet beside the first. The difference was $612.
The insurer did not describe the change as a refund or admit that every part of the earlier quote was wrong. A quote is an estimate, and prices can change when its inputs change. The useful comparison was narrower: with the old address link removed and the selected coverage held steady, the automated price fell by 28 percent.
That did not prove the former address alone carried a $612 surcharge. A predictive model may recalculate several interacting features when one household link changes. Removing an address can alter the rating territory while also changing which vehicles or losses the system considers connected.
The two sheets showed the consequence without revealing the full formula.
The correction did not erase the data trail
The old house remained part of Elena’s address history after the review. That was accurate. The correction changed its status from an apparently active risk connection to a past address, at least within the records used for the revised quote.
This difference matters because deleting a true historical record and correcting an inference are not the same act. Elena had lived at the house. Her dispute concerned what the system concluded from that fact fourteen months later.
The episode also left her with a privacy tradeoff she had not expected. To challenge the machine’s inferred household, she had to provide newer records with more personal information. The company needed enough evidence to separate two lives that its model had joined, while Elena had little visibility into which source created the link or whether the change would reach every system that might use it later.
Insurance data can move through outside reporting services and internal databases with different update schedules. A correction in one quoting workflow does not necessarily rewrite the original source. In Elena’s case, the support team confirmed the revised quote, but she did not receive a map of the data path and could not tell whether another insurer would make the same match.
She bought the $1,572 policy. The decision was practical rather than celebratory. The price fit her budget, the coverage matched what she had requested, and the old address no longer appeared as active on the quote.
She kept both sheets.
Questions people ask
Can an old address affect a current insurance quote?
It can when an automated system treats the address as evidence about current location, household membership or connected claim history. In Elena’s case, the old home was not merely stored as history. An identity-matching model classified it as an active link and sent that inference into the pricing process.
Why was the old address used when the account page was correct?
The account page showed Elena’s mailing and vehicle information, while the quote drew from a broader risk profile built from current and historical records. Those systems answered different questions, so one displayed her new address even as another assigned confidence to the former household connection.
Does a $612 reduction show what the old address cost?
No single line on Elena’s quote assigned $612 to the address. Removing the link caused the model to recalculate territory and connected-risk features together. The two quotes, with coverage held steady, showed a $612 difference between outputs rather than an itemized address charge.
Did correcting the quote remove the former home from every record?
No. The house remained a valid part of Elena’s history, and the review changed how it was classified for that quote. She was not shown whether the correction reached outside data sources or other internal systems. Her two sheets recorded only the visible result: $2,184 on the first and $1,572 on the second.
One story a day
The story of the day, in your inbox
One real story about AI each morning — no hype, no alarm, just company for the road.